Private Investments Versus Public Markets: A Strategic Comparison for 2026

Reblogged from exiorinvestments.com

Originally published at:

The content below is republished with permission.
Liquidity is not the same as clarity. The choice between private investments and public markets is rarely a simple contest between potential returns and ease of access. Publicly quoted prices offer an immediate reference point, while private valuations are periodic and depend on underlying assumptions. Neither feature, on its own, tells you whether an investment fits your objectives.
Listed assets can be easier to price at a glance, while the timing of an exit from a private investment may be harder to forecast. But a sound comparison requires more than a price screen. Market structure affects how an asset is valued, when capital can be redeployed and what information is available for oversight. Assess liquidity, valuation, disclosure, governance and investor influence together to understand the trade-offs.
This article sets out a consistent framework for comparing both markets in 2026, without treating either as the default choice. You’ll see which questions warrant closer analysis and how deal-by-deal access can focus attention on an individual opportunity. For investors in the UAE, private-capital and portfolio advisory can help place those decisions within a broader allocation strategy.

Key Takeaways

  • Compare private investments versus public markets by structure, not by assuming one offers superior returns.
  • Separate the ability to access a market from the ability to exit an investment when you choose.
  • Assess price visibility, disclosure and governance alongside liquidity. Each can vary by security, vehicle and jurisdiction.
  • Start portfolio decisions with your objectives, liquidity needs and investment horizon, then consider existing exposures.
  • Use deal-by-deal analysis and portfolio advisory to assess how an individual private opportunity fits your broader allocation.

Table of Contents

Private Investments Versus Public Markets: What Is the Difference?

Private investments are interests in companies, loans, or assets arranged outside public exchange trading. Publicly traded securities, such as listed shares and bonds, are bought and sold on public markets through an exchange or a market intermediary. The distinction concerns how investments are accessed, traded, and disclosed. It does not determine their quality, risk,k or potential outcome.
The central distinction is structural: private investments are accessed through specific transactions or vehicles, while public securities trade through established markets with observable quotations. Both categories contain different assets and terms, so the label alone cannot tell you how a particular investment will behave.

How do private-market asset classes differ in portfolio function?

Private equity may be assessed for long-term growth exposure, while private credit may be considered for income-oriented exposure. Real estate and infrastructure can provide exposure to real assets, but the underlying economics and investment structures vary widely. None of these categories guarantees a particular result.
Structure matters. An equity investment may involve participation in a company’s ownership and value development; a credit investment is shaped by its lending terms and repayment profile. Real-asset investments may provide exposure through different ownership or financing arrangements. Each structure can affect investor control, cash-flow timing, valuation methods, and the potential holding period. These are portfolio-level distinctions, not substitutes for assessing a specific transaction’s terms, risks, and documentation.

What qualifies as a private investment?

Broad categories include private equity, which involves investing in companies that aren’t publicly listed; private credit, which involves lending arranged outside public bond markets; and real assets, such as property or infrastructure interests. These are distinct asset categories, not interchangeable structures. For background on one category, see What is Private Equity?

The structure can affect an investor’s rights, the information they receive and their ability to transfer an interest. Terms vary by opportunity. A private investment may have a defined process for entry and exit, but private status alone doesn’t establish when an exit will be possible.

What does investing in public markets mean?

Investors typically buy or sell listed shares and bonds through an exchange or a market intermediary. Publicly traded securities commonly have visible quotations that change as orders meet and market conditions shift. Those prices reflect current trading, not a guarantee that a transaction can be completed at that price or at any particular moment.
Market access and liquidity are related, but they aren’t identical. Market conditions, the security’s trading activity, or other constraints may limit trading. Public disclosure can also help assess an issuer, though the level of detail and timing depend on the security and applicable requirements.
For investors in the UAE comparing private investments versus public markets, start by identifying the structure behind each opportunity. Consider how it is accessed, what information is available, how ownership rights are defined, and what rules apply to transfers. These details provide a more precise basis for comparison than assuming private or public status signals a superior investment.

How Private and Public Investments Differ in Liquidity, Valuation and Disclosure

Liquidity, valuation,n and disclosure are connected, but they answer different questions. Liquidity concerns how readily an investor can sell or transfer an interest. Valuation concerns how its worth is assessed. Disclosure determines what information is available to evaluate that assessment. Comparing private investments versus public markets means examining all three, rather than treating a quoted price as proof of an easy exit or a private valuation as proof of stability.

How does liquidity affect access to capital?

Exchange trading can provide more frequent opportunities to transact, but a sale still depends on market conditions, buyer demand, and the security’s trading activity. A quoted price does not guarantee an immediate transaction at that level. In a stressed market, the price available to a seller may differ from the most recent quotation.
Private investment structures can have holding periods, transfer restrictions, or exit processes that differ by opportunity. An investor may need to wait for a specified event, a buyer, or another permitted transfer route. The practical question is not simply whether an investment is labeled liquid or illiquid. Consider whether you may need the capital for planned withdrawals, obligations, or other portfolio decisions before an exit becomes feasible.

Why can private investment valuations look different?

Public securities commonly have observable trading prices that update as transactions occur. These prices offer frequent reference points, though they reflect current trading conditions rather than a certain future sale value. Private investments may be valued periodically using financial analysis, asset information, or relevant transaction evidence. As a result, reported values may update less often than public quotations.
That difference in timing matters. A private portfolio value can appear unchanged between valuation points even as underlying conditions evolve; a listed security’s quotation may register market movements more continuously. Neither timing convention eliminates risk or guarantees that an investor can realize the stated value. A valuation is an assessment at a point in time, not a promise of proceeds.

Consider liquidity, valuation frequency and time horizon together: the less frequently an investment can be priced or transferred, the more carefully its timing should align with your capital needs.

Disclosure also shapes the assessment. Public issuers generally report under applicable market rules, while private investment reporting depends on the vehicle, documents, and governing arrangements. More frequent information does not remove investment risk. Consider less frequent reporting alongside the detail provided and the investor’s rights.

Private-capital and portfolio advisory can help frame these mechanics against allocation objectives and liquidity needs. Explore private-capital advisory as part of a disciplined review of how an individual opportunity fits within a broader portfolio.

Private Investments Versus Public Markets: A Side-by-Side Comparison

A consistent comparison starts with mechanics, not assumptions about performance. The table outlines common distinctions, but each characteristic can change with the security, investment vehicle, jurisdiction, and specific terms.
Criterion Private Investments Public-Market Securities
Liquidity Sale or transfer may depend on vehicle rules, restrictions, buyer availability, or a defined exit process. Exchange trading can provide more frequent opportunities to transact, subject to market activity and conditions.
Price Visibility Valuations may be updated periodically using analysis or transaction evidence. Listed securities commonly have observable market quotations that change with trading.
Disclosure Reporting and information rights depend on the investment documents, vehicle, and applicable requirements. Issuers generally make disclosures under requirements that apply to their market and security.
Governance Investor rights may be set out in governing documents and can vary by structure and ownership position. Rights are generally linked to the security, issuer arrangements, and applicable market rules.
Access Entry may be through a specific transaction or investment vehicle, subject to its terms. Investors typically transact through an exchange or market intermediary.
Typical Holding Horizon May be longer or less predictable where transfer and exit options are limited. Can be adjusted through market transactions, though execution and price depend on conditions.

Which trade-offs should investors compare first?

Begin with the capital’s intended purpose and timing. Compare liquidity needs with planned withdrawals, obligations, and investment horizon. Then examine how often the investment is valued, what information investors receive,e and which governance rights apply. These details matter at the opportunity level, not just at the asset-class level.
Assess diversification by looking through the label to the underlying exposures. A private vehicle and a listed fund may both hold assets linked to the same sector or economic driver. Adding a private or public allocation does not, by itself, make the portfolio more diversified.

Does one market offer better returns or lower risk?

No market structure guarantees higher returns or lower risk. Realized outcomes can be affected by asset selection, entry price, fees, leverage and execution, among other factors. A meaningful performance comparison requires dated evidence using comparable assets, periods and measurement methods. Without that basis, broad return claims can mislead.
Market structure alone cannot determine portfolio suitability. Fit depends on how an investment’s exposures, rights, valuation process, and liquidity align with the investor’s objectives. Use the comparison as a due-diligence framework, then evaluate the specific opportunity and its role within the wider allocation.

How to Decide Whether Private or Public Investments Fit Your Portfolio
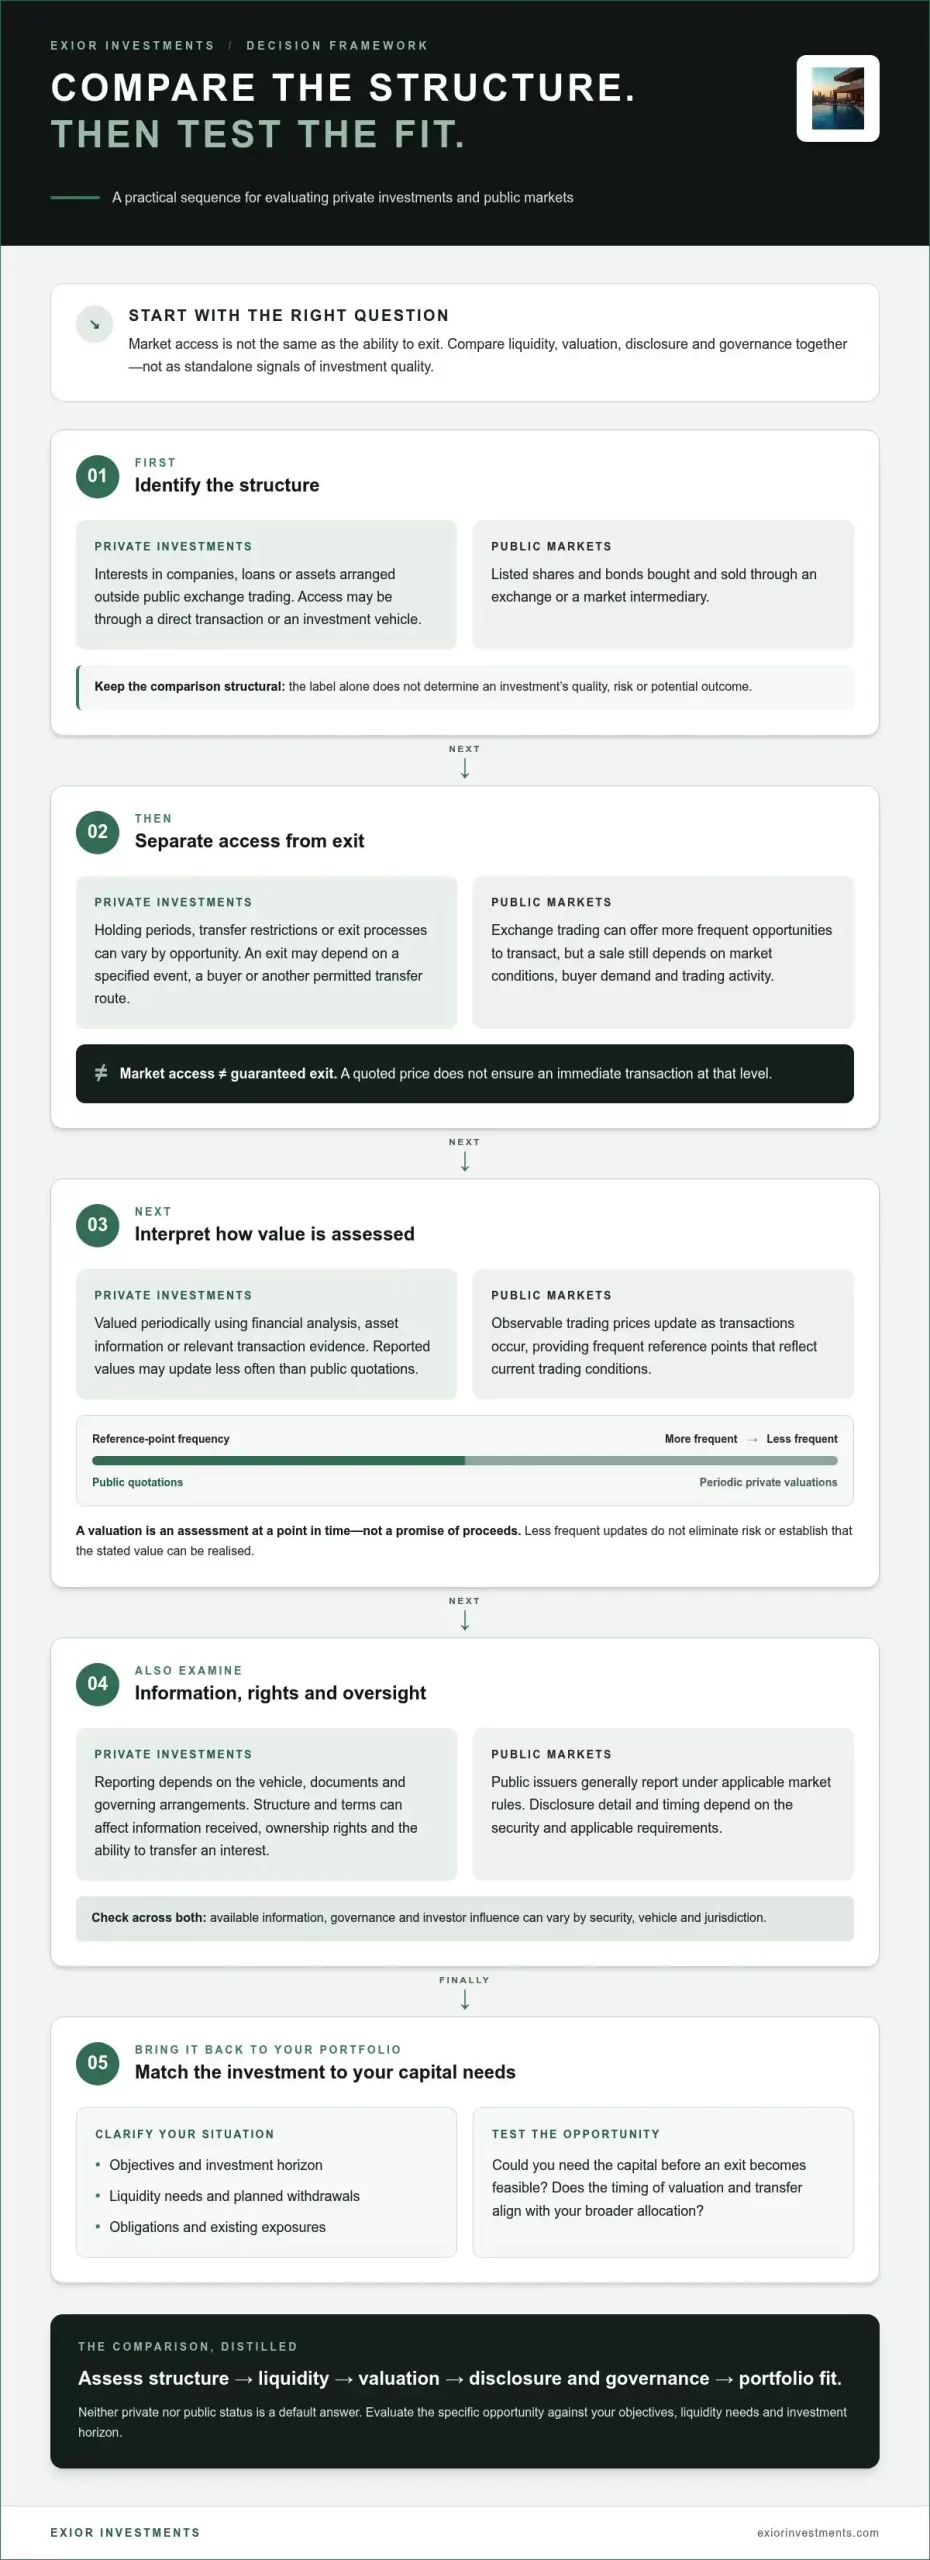
Choose a market structure only after defining the role an investment must play. This framework helps UAE investors assess private investments versus public markets based on portfolio objectives, liquidity, existing exposures, and opportunity-specific terms.
  1. Define the objective and time horizon. Identify what the capital is intended to support and when it may be needed. A long investment horizon may allow more flexibility, but it does not remove the need to understand exit conditions.
  2. Map liquidity needs. Account for planned withdrawals, obligations, and other commitments before considering capital that may be harder to transfer. Distinguish your financial capacity to bear risk from your willingness to accept uncertainty or limited access to capital.
  3. Review the current portfolio. Review existing holdings to identify concentrations by asset, sector, geography,y or economic exposure. Consider whether a new investment adds a distinct exposure or reinforces risks already present. A private or public label alone does not create diversification.
  4. Examine the specific opportunity. Review the investment terms, governance and investor rights, reporting arrangements, valuation approach, and transfer or exit provisions. Assess the underlying risks and how leverage, execution,n and fees may affect the investment. Focus on the documents and mechanics of the opportunity, not broad assumptions about its category.
  5. Identify jurisdiction-specific questions. For a UAE-based investor, legal and tax considerations can depend on the investor, structure, and relevant jurisdictions. Have those questions reviewed by appropriately qualified professionals using current information before making a commitment.
The sequence matters. If near-term capital needs conflict with transfer restrictions or an uncertain exit timeline, address that mismatch before considering expected return. If an investment appears to complement existing exposures, examine its underlying risks and terms to determine whether the fit is substantive.
Private-capital and portfolio advisory can help connect an individual opportunity with broader allocation objectives. Deal-by-deal access also allows each opportunity to be considered on its own characteristics rather than treated as interchangeable with private markets as a whole.

This framework supports informed analysis; it does not replace advice tailored to an investor’s circumstances. Discuss private investment portfolio fit with EXIOR Investments as part of a disciplined review of your objectives and constraints.

How Private Capital Advisory Can Support a Disciplined Comparison

Comparing private investments versus public markets is most useful when analysis moves from general characteristics to the terms and role of a specific opportunity. Private-capital advisory can connect that assessment to an investor’s objectives, existing exposures, liquidity requirement,s and investment horizon. It doesn’t make an opportunity suitable by default; it helps clarify the questions that should shape a considered decision.

What can deal-by-deal investment access add to the analysis?

Deal-by-deal access places an individual opportunity at the center of review. Rather than treating private investments as a single category, an investor can examine the proposed structure, underlying exposure and relevant terms on their own merits. Key areas include how valuation is assessed, which governance and reporting arrangements apply, how transfers or exits are addressed, and how the investment fits within the wider portfolio.
This level of analysis helps distinguish access from suitability. An opportunity’s availability does not establish its quality, alignment or likely outcome. EXIOR Investments provides deal-by-deal investment access alongside private-capital advisory, supporting a structured review of the opportunity and its relationship to the investor’s objectives and constraints.

When can portfolio advisory complement private investment analysis?

Portfolio advisory brings the broader allocation into view. It can help frame whether a proposed investment adds a distinct exposure or increases concentration, and whether its potential liquidity profile is consistent with other portfolio commitments. For investors assessing private-market exposure to real assets, real-asset advisory can inform opportunity-level analysis within that allocation context.
Structured finance may also be relevant when an investor’s needs require consideration of financing structure. Its role should be assessed in light of the specific opportunity and portfolio constraints, not assumed to improve an investment’s suitability. Across these capabilities, the focus is disciplined comparison: underlying exposure, investment structure, governance, valuation and portfolio fit.

For investors in the UAE, this analysis can be tailored to their objectives and portfolio context without relying on broad claims about public or private markets. A considered discussion can help identify which trade-offs merit deeper examination before committing capital. To explore how private capital and portfolio advisory may relate to your objectives, speak with EXIOR Investments.

Make the Structure Serve Your Strategy

The choice between private investments versus public markets is not a verdict on which market is superior. It is an allocation decision shaped by your objectives, time horizon, and need for access to capital. Public quotations can offer frequent price references, while private investments may involve less frequent valuations and more specific transfer provisions. Neither feature alone establishes suitability or outcome.
Compare liquidity, valuation, disclosure and governance together, then assess how an opportunity’s underlying exposures relate to the wider portfolio. The label matters less than the structure, rights and risks attached to the investment. A disciplined review brings those details into focus before capital is committed.

EXIOR Investments offers deal-by-deal investment access, private-capital and real-asset advisory, and portfolio advisory. These capabilities can help connect an individual opportunity to broader allocation considerations without assuming that access guarantees fit or results.
For a considered discussion of how private capital may relate to your objectives, discuss a private-capital strategy with EXIOR Investments. A clear framework supports deliberate investment decisions.

Frequently Asked Questions

What is the main difference between private investments and public markets?
Private investments are generally arranged outside public exchanges, while public-market securities trade through exchange or market systems. This affects how investors access opportunities, observe prices, receive information,n and potentially exit. The phrase private investments versus public markets describes differences in market structure, not a ranking of quality. The terms of a private investment and the trading conditions for a public security still matter, and neither label alone determines suitability, risk, or expected performance.
Neither category is universally riskier; the risks differ by investment. Private investments may involve limited liquidity and less frequent valuations, while public securities can experience price volatility and changing trading conditions. Underlying assets, structure, leverage, governance, and investor rights also affect risk. Compare each opportunity with your objectives, existing portfolio exposures,s and financial capacity to hold through uncertainty. A market label by itself is not a sufficient basis for judging risk.
Sometimes, but an early sale or transfer depends on the investment’s legal structure, terms,ms and potential buyers. The documents may restrict transfers, require approvals, or specify a time-consuming process. Even if a sale is permitted, a buyer may not be available when needed, and the exit value may differ from the latest valuation. Review exit provisions before committing and consider whether you can keep the capital invested for longer than planned.
Public securities often have observable market quotations that can change during trading. Private investment valuations may instead rely on periodic analysis, transaction evidence, or other methods, so reported values may update less frequently. Each valuation reflects an assessment at a particular time; it does not guarantee the amount an investor could receive in a sale. Compare the valuation approach, information used,d and reporting cadence when evaluating an opportunity.
No. A private structure does not guarantee higher returns, and outcomes depend on the investment and its execution. Asset selection, entry price, fees, leverage, timing, and investment duration can all influence realized results. Historical performance may not be directly comparable across strategies or periods, particularly when valuation methods differ. Assess the underlying opportunity, its risks and its place in your portfolio rather than treating access to private markets as evidence of superior performance.
Your options depend on the investment terms, transfer restrictions, potential buyers, and prevailing conditions. There may be no immediate exit, or a sale may not be possible on your preferred timeline or at your expected valuation. Before investing, map upcoming obligations against the period your capital may need to remain committed. Treat any anticipated exit route as a possibility to assess, not as guaranteed liquidity or access to cash on demand.
There is no general rule that private investments should replace publicly traded holdings. The appropriate allocation depends on your objectives, liquidity needs, time horizon, existing exposures, and tolerance for uncertainty. Public and private investments may serve different roles, but diversification depends on the underlying assets and risks, not the labels alone. Consider each proposed allocation within the whole portfolio, and seek qualified advice suited to your circumstances where appropriate.
More Post